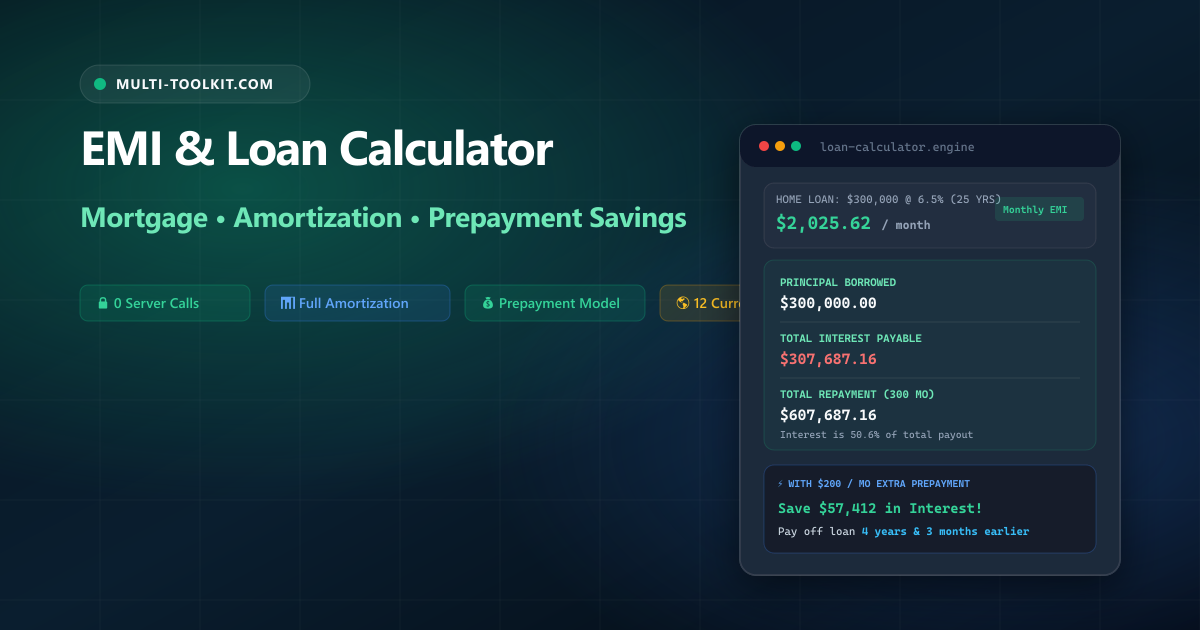
Stop guessing loan interest and bank amortization curves: calculate monthly EMI, simulate extra prepayment savings, and export complete repayment schedules 100% inside your browser.
Whether financing a family home with a 25-year mortgage, purchasing a car, consolidating credit card balances, or taking out a commercial business loan, borrowing capital is one of the most critical financial commitments an individual or business will ever make. On a standard \$300,000 mortgage at 6.5% interest over 25 years, a borrower will repay over \$307,000 in interest alone—surpassing the original principal borrowed.
Yet borrowers frequently evaluate loan offers based strictly on the monthly installment quoted by bank sales representatives. Searching Google for an emi calculator or loan calculator online often leads to predatory lead-generation websites that demand personal phone numbers and emails (triggering aggressive sales calls from brokers) or simple tools that hide the month-by-month amortization schedule.
The Multi-Toolkit EMI & Loan Calculator delivers complete, unbiased financial transparency with 100% client-side privacy.
The borrowing trap: why banks profit from interest front-loading
1. The front-loaded amortization curve
On long-term loans (such as 20- or 30-year mortgages), banking mathematics structure your repayment so that early payments consist of nearly 80% interest and only 20% principal. During the first five years of repayment, despite paying tens of thousands of dollars, your principal balance barely decreases.
2. The “flat rate” vs “reducing balance” marketing trap
Auto dealerships and personal loan providers frequently market loans using “flat interest rates” (e.g. “Only 4.5% flat rate per annum!”). A flat rate calculates interest on the entire original loan amount for the whole tenure, ignoring repayments. A 4.5% flat rate on a 5-year loan corresponds to an effective reducing-balance APR of nearly 8.3%—almost double the advertised number.
3. The tenure extension illusion
Lenders frequently encourage borrowers to stretch loan tenures from 15 to 30 years by advertising lower monthly installments. While the monthly cash requirement drops, the total lifetime interest paid often triples, turning an affordable purchase into a massive wealth drain.
4. Predatory lead-gen brokers and spam calls
Entering your personal financial figures into traditional loan aggregator sites often triggers automated lead distribution, resulting in persistent sales calls and unwanted hard credit inquiries.
In-browser architecture: how Multi-Toolkit computes amortization locally
Multi-Toolkit calculates all monthly installments, interest breakdowns, prepayment simulations, and CSV exports directly in your browser’s JavaScript runtime with zero server requests.
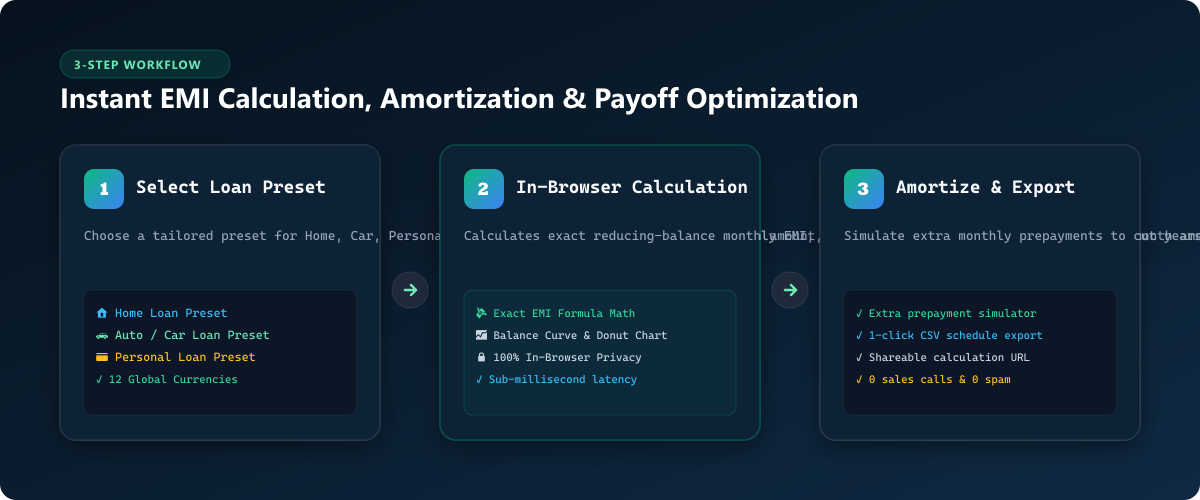
1. Preset Ingestion
Choose tailored 1-click baselines for Home, Car, Personal, Education, or Business debt with flexible principal, rate, and tenure inputs.
2. Actuarial Math
Applies standard reducing-balance annuity formulas, generating exact monthly EMI, total interest, and visual balance curves in RAM.
3. Prepayment & CSV
Simulates extra monthly contributions to calculate interest dollars saved, tenure shortened, and provides 1-click CSV download.
Core features & capabilities
| Feature | Multi-Toolkit Loan Studio | Bank Official Portals | Generic Web Calculators |
|---|---|---|---|
| Privacy & Data Security | 100% In-Browser (0 Data Sent, No Signup) | Lead Capture (Phone & Email Required) | Ad Trackers & Cookies |
| Loan Type Presets | Home, Car, Personal, Education, Business | Single Product Form | Generic Single Form |
| Full Amortization Schedule | Month-by-Month Interactive Table | Summary Only / Gated | Yearly Summaries Only |
| Prepayment Savings Model | Exact Interest Saved & Months Shortened | Unsupported | Rarely Supported |
| Schedule Export | 1-Click CSV Download for Excel | Unsupported | Unsupported |
| Multi-Currency Support | 12 Currencies (USD, EUR, GBP, INR, AED, SAR...) | Single Domestic Currency | USD (\$) Only |
Step-by-step interactive guide
- Select Loan Preset & Input Terms: Open the EMI & Loan Calculator. Choose a loan preset (Home, Car, Personal, Education, or Business) to load typical parameters, or customize your Principal loan amount, annual interest rate percentage, and loan tenure (in years or months).
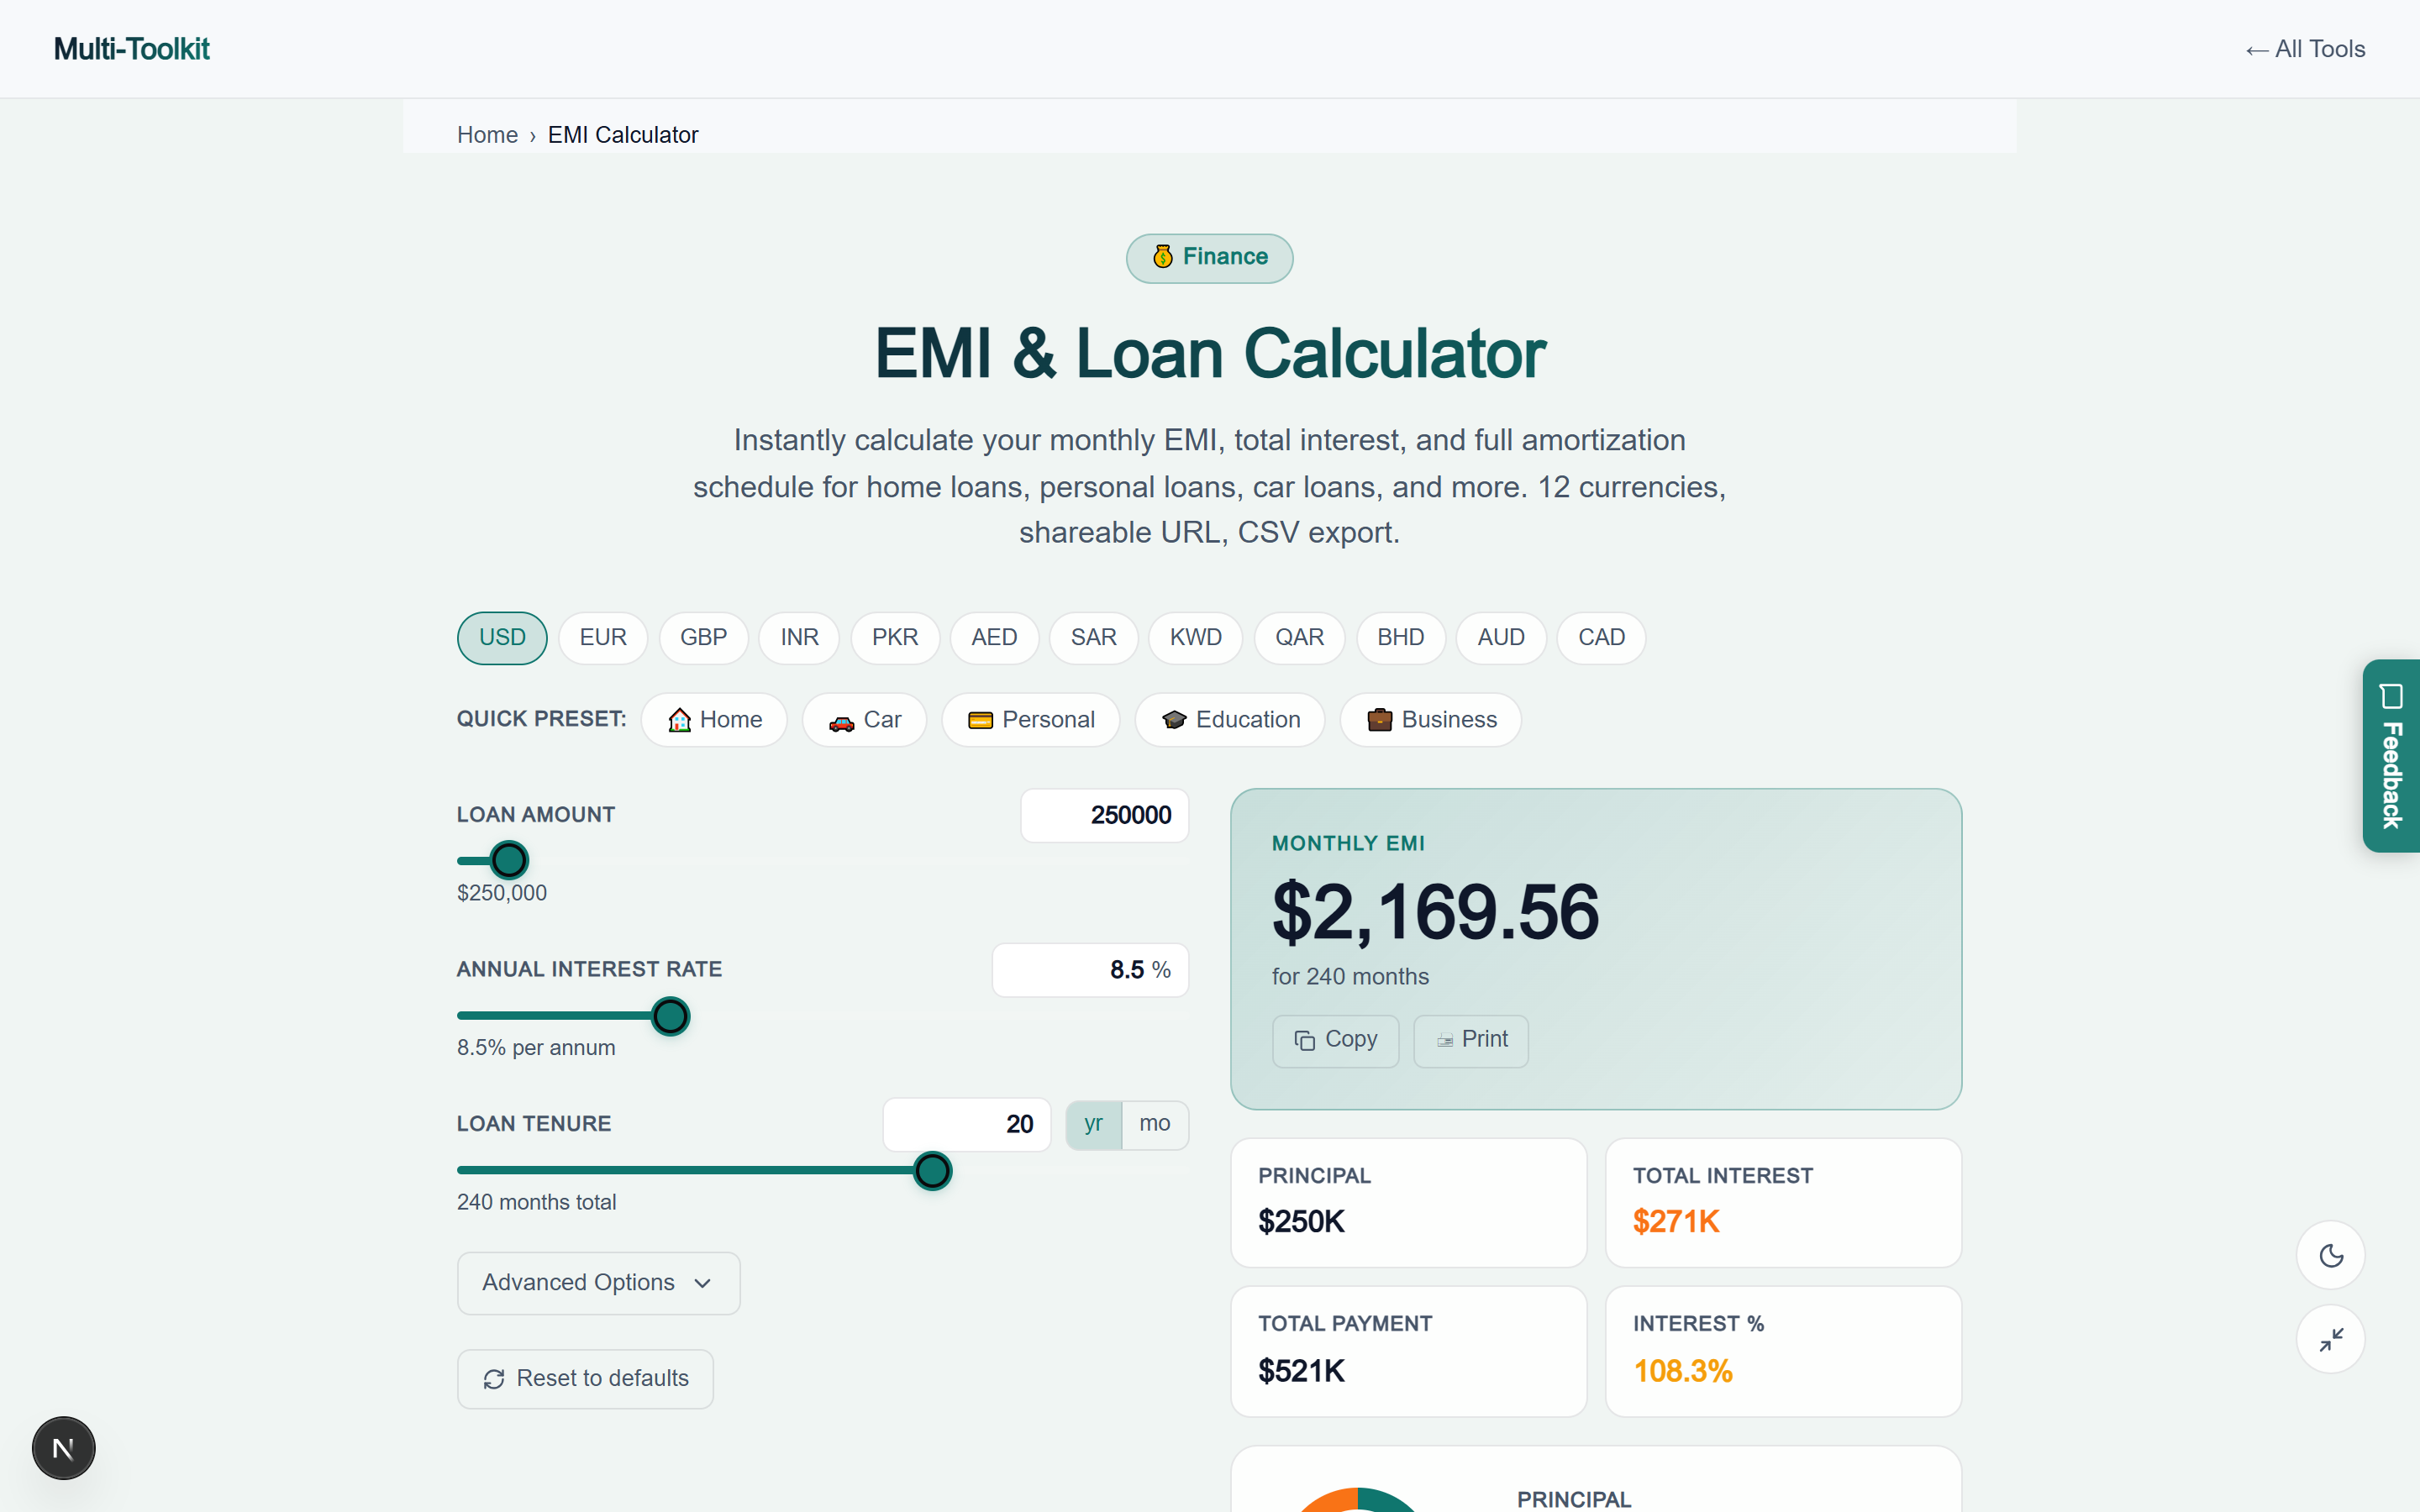
- Examine Monthly EMI & Total Interest: The summary card immediately presents your monthly EMI, total interest payable, total repayment amount, and a visual donut chart illustrating the principal vs interest percentage split.
- Model Prepayments & Fees: Open the Advanced Options tab to factor in upfront down payments, processing fees, or extra monthly prepayments. The Prepayment Callout will instantly calculate your total interest savings and how many months are shaved off your loan.
- Inspect Schedule & Export CSV: Scroll down to the Amortization Schedule table to inspect month-by-month balance reductions, or click “Download CSV” to save the complete repayment schedule for spreadsheet modeling.
Visual interface showcase: light & dark modes
Light Mode Interface
Dark Mode Interface
Five critical borrowing pitfalls to avoid
Pitfall 1: Confusing “flat rate” with “reducing balance”
Always ask lenders for the true Reducing Balance APR. A 5% flat rate on a 4-year loan is mathematically equivalent to a 9.15% reducing rate. Never compare flat rates directly against mortgage reducing rates.
Pitfall 2: Optimizing strictly for monthly payments rather than total cost
Extending loan tenure reduces monthly cash outflow but dramatically inflates total interest. Always evaluate the Total Interest Payable before choosing a longer repayment horizon.
Pitfall 3: Ignoring upfront processing fees & insurance add-ons
A loan with a 6.0% rate and a 3.0% upfront processing fee can cost more than a loan with a 6.25% rate and zero fees. Always input upfront fees into the calculator to evaluate the true net borrowing cost.
Pitfall 4: Overlooking prepayment penalties
Check whether your lender charges penalties for partial prepayments or early settlement. In many regulatory jurisdictions (such as the US, UK, and GCC), prepayment penalties on retail consumer loans are prohibited or capped.
Pitfall 5: Failing to inspect the amortization schedule
Never sign loan paperwork without reviewing the month-by-month amortization schedule. Seeing how little principal is paid off during years 1 through 5 is the best motivator to start early prepayments.
Effective prepayment strategies: accelerate debt freedom
| Prepayment Strategy | Implementation Mechanism | Impact on \$300K 25-Yr Mortgage (6.5%) |
|---|---|---|
| Monthly Micro-Prepayment | Add \$100 to \$250 extra every month directly to principal. | Saves \$35,000 to \$68,000; shortens loan by 2.5 to 5 years. |
| 13th Payment Strategy | Make 1 extra full monthly EMI once per year (e.g. from an annual bonus). | Saves ~\$42,000; cuts nearly 4 years off debt. |
| Bi-Weekly Payment Hack | Pay half your EMI every 2 weeks (26 half-payments = 13 full payments/year). | Seamlessly achieves the 13th payment strategy with zero budgeting friction. |
Security & privacy architecture
Your financial details and loan plans should remain confidential:
- No Phone Number or Email Required: You never have to submit contact details or create an account.
- 100% Client-Side Calculations: All interest computations, balance graphs, and CSV data are generated inside your browser memory. No financial figures are ever sent to our servers.
- Zero Marketing or Lead Brokering: We do not sell mortgage leads or loan applications to third-party lenders.
Frequently asked questions
What is EMI and how is it calculated?
EMI stands for Equated Monthly Installment. It is calculated using the standard reducing balance formula: EMI = [P × r × (1+r)^n] / [(1+r)^n – 1], where P is the principal borrowed, r is the monthly interest rate (annual rate / 12 / 100), and n is the total number of monthly installments.
What is the difference between flat rate and reducing balance interest?
A flat interest rate charges interest on the original loan principal for the full loan tenure, resulting in an effective APR nearly double the quoted rate. A reducing balance rate calculates monthly interest strictly on the remaining unpaid principal balance.
How do extra prepayments save money on a loan?
Prepayments go 100% directly toward reducing the outstanding principal balance. By lowering the principal balance early, all future interest calculations are reduced, saving thousands in total interest and shortening the repayment tenure.
Can I export the full amortization schedule to Excel or Google Sheets?
Yes. Click the “Download CSV” button in the Amortization Schedule section to export the complete month-by-month table including beginning balance, EMI, principal, interest, and closing balance.
Which currencies are supported by the loan calculator?
Multi-Toolkit supports 12 global currencies: USD (\$), EUR (€), GBP (£), INR (₹), PKR (Rs), AED (AED), SAR (SAR), KWD (KWD), QAR (QAR), BHD (BHD), AUD (A\$), and CAD (C\$).
Are my loan details or salary figures transmitted across the internet?
No. All calculations, charts, and amortization schedules are computed 100% locally inside your browser memory. No financial data is ever sent to any server.
Explore related financial & productivity tools
Plan your financial independence with these free utilities on Multi-Toolkit:
- Compound Interest Calculator — Visualize long-term investment growth, compounding frequencies, and recurring deposits.
- Salary & Net Pay Calculator — Calculate net take-home salary and allowances across GCC and international contracts.
- End of Service Gratuity Calculator — Calculate UAE, Saudi Arabia, and GCC severance pay accurately.
- VAT & Sales Tax Calculator — Compute standard, reverse, and inclusive/exclusive value-added tax.
- Percentage Calculator — Calculate percentage increases, discounts, and markups instantly.
Calculate monthly EMI, model prepayment savings, and export full amortization schedules—100% in your browser with complete privacy:
Open Free Loan & EMI Calculator →